
2026-11-16 09:00:00 • Calibration: 2026-11-09
Synthetic & Wrapper · Primary SEO Target: sUSDe / Ethena USDe Yield & Risk Rating
Ethena sUSDe Risk Rating: What Happens When Funding Flips Negative and 35% of Supply Is Looped?
Week 1 TokenLab v2.1 RWA audit for sUSDe (Ethena): Safety Grade B (66.9/100), 30% run queue 1 mo (-0.13% exit discount), Safe LTV 84.0% (USD 215M cap).
Every Monday for ten weeks, Linas Stankevičius and I publish one deep institutional tear-sheet from our 32-vault TokenLab v2.1 RWA & DeFi Risk Benchmark. This Week 1 teardown examines Ethena (sUSDe)—specifically why delta-neutral perpetual basis wrappers carry structural cash-buffer and negative-funding exposure that 7-day cooldowns cannot mask during leveraged Pendle and Morpho unwinds.
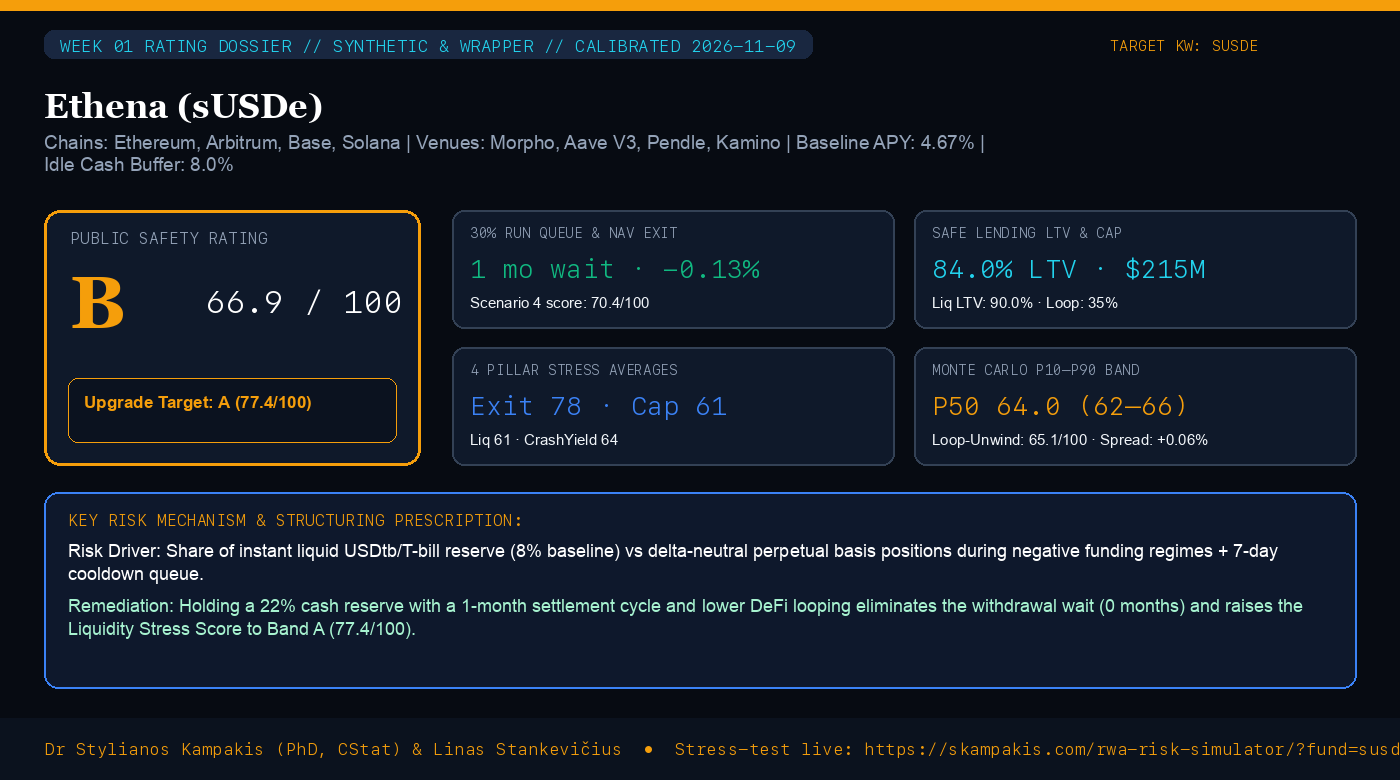
2026-11-09 across 9 stress scenarios and 100 Monte Carlo paths per regime.1. Structural Classification & Where sUSDe Sits in the 32-Vault v2.1 Universe
Across the expanded TokenLab v2.1 32-vault universe (2026-11-09), every tokenised yield product falls into one of three distinct architectural classes: 16 Direct RWA Funds backed by legal claims on Treasuries or private credit, 11 DeFi Curated Vaults managed via non-custodial ERC-4626/Solana lending allocations, and 5 Synthetic & Wrapper Structures relying on delta-neutral perpetual basis, Pendle principal separation, or multi-hop leverage.
Within that map, sUSDe operates on Ethereum, Arbitrum, Base, Solana across Morpho, Aave V3, Pendle, Kamino and carries an estimated scale of $1.21B Staked ($4.99B USDe). Under European regulatory taxonomy, we classify its disclosure perimeter as Title III (Asset-Referenced / Synthetic Reserve Disclosure). Its primary structural transmission lag stems from 7-Day Cooldown (~0.25–1 mo stress lag) against a 8.0% ready liquid cash reserve.
Comparing across tiers explains why nominal APY misleads allocators. At the sovereign top of the v2.1 matrix, Superstate USTB (99.6, A+) and BlackRock BUIDL (99.4, A+) clear a 30% withdrawal wave in 0 months with zero secondary discount. Meanwhile, poorly buffered or strictly gated wrappers sit at the opposite extreme: Apollo ACRED (53.3, D) builds a 14-month FIFO exit queue (-5.51% discount), and 56%-looped reinsurance ONyc sheds -18.8 points during a leverage unwind even though 95%-looped auto credit AUTO (70.7, B+) settles faster.
2. Complete 9-Scenario Accrual Stock-Flow Stress Matrix for sUSDe
Marketing fact sheets quote Scenario 1 (Calm Baseline: 73.5/100 score and 4.67% net annualised TWR for sUSDe). Institutional risk committees must instead price Scenarios 4 through 9, where concentrated redemptions, delayed asset settlement, reduced external market depth, and correlated lending unwinds collide. Every row below runs 36 monthly discrete-time steps under strict accrual-basis conservation (stock-flow reconciliation tolerance below 1e-6):
| Stress Regime | Investor Score | Net TWR APY | Forced-Exit TWR | Max Queue Wait | Worst NAV Discount | Max Drawdown | Min LCR | Conservation |
|---|---|---|---|---|---|---|---|---|
| 1. Baseline (current terms, normal turnover) | 73.5 | 4.67% | 4.64% | 0 mo (avg 0.00) | -0.10% | -0.00% | 0.08x | Pass (<1e-6) |
| 2. Low inflows / stagnant AUM | 73.5 | 4.52% | 4.49% | 0 mo (avg 0.00) | -0.10% | -0.00% | 0.08x | Pass (<1e-6) |
| 3. Rate cut and credit write-downs | 69.3 | 2.33% | 2.29% | 0 mo (avg 0.00) | -0.10% | -1.51% | 0.08x | Pass (<1e-6) |
| 4. Concentrated institutional run | 70.4 | 4.61% | 4.41% | 1 mo (avg 0.03) | -0.13% | -0.00% | 0.08x | Pass (<1e-6) |
| 5. Loan rollover freeze and longer settlement | 70.6 | 4.63% | 4.44% | 1 mo (avg 0.00) | -0.10% | -0.00% | 0.00x | Pass (<1e-6) |
| 6. Liquidity-provider pullback (75% facility cut) and redemption wave | 73.5 | 4.63% | 4.59% | 0 mo (avg 0.00) | -0.10% | -0.00% | 0.08x | Pass (<1e-6) |
| 7. Combined crisis (rate cut, defaults, run, settlement freeze) | 51.6 | 2.40% | -1.58% | 2 mo (avg 0.25) | -2.38% | -2.14% | 0.01x | Pass (<1e-6) |
| 8. Severe institutional run (35% institutional + 20% family offices) | 58.5 | 4.53% | 2.13% | 2 mo (avg 0.26) | -2.20% | -0.00% | 0.00x | Pass (<1e-6) |
| 9. Looping unwind (borrow-rate spike forces looped holders out) | 65.1 | 4.56% | 4.11% | 1 mo (avg 0.19) | -0.30% | -0.00% | 0.08x | Pass (<1e-6) |
Notice two diagnostic signals in Table 1. First, under Scenario 4 (30% Institutional Run), sUSDe records a 1-month maximum time-to-payment wait and a -0.13% no-arbitrage secondary discount—translating into a Scenario 4 investor score of 70.4/100. Second, under Scenario 7 (Combined Adverse Crisis), its annualised return adjusts to 2.40% with a worst-case crisis score of 51.6/100.
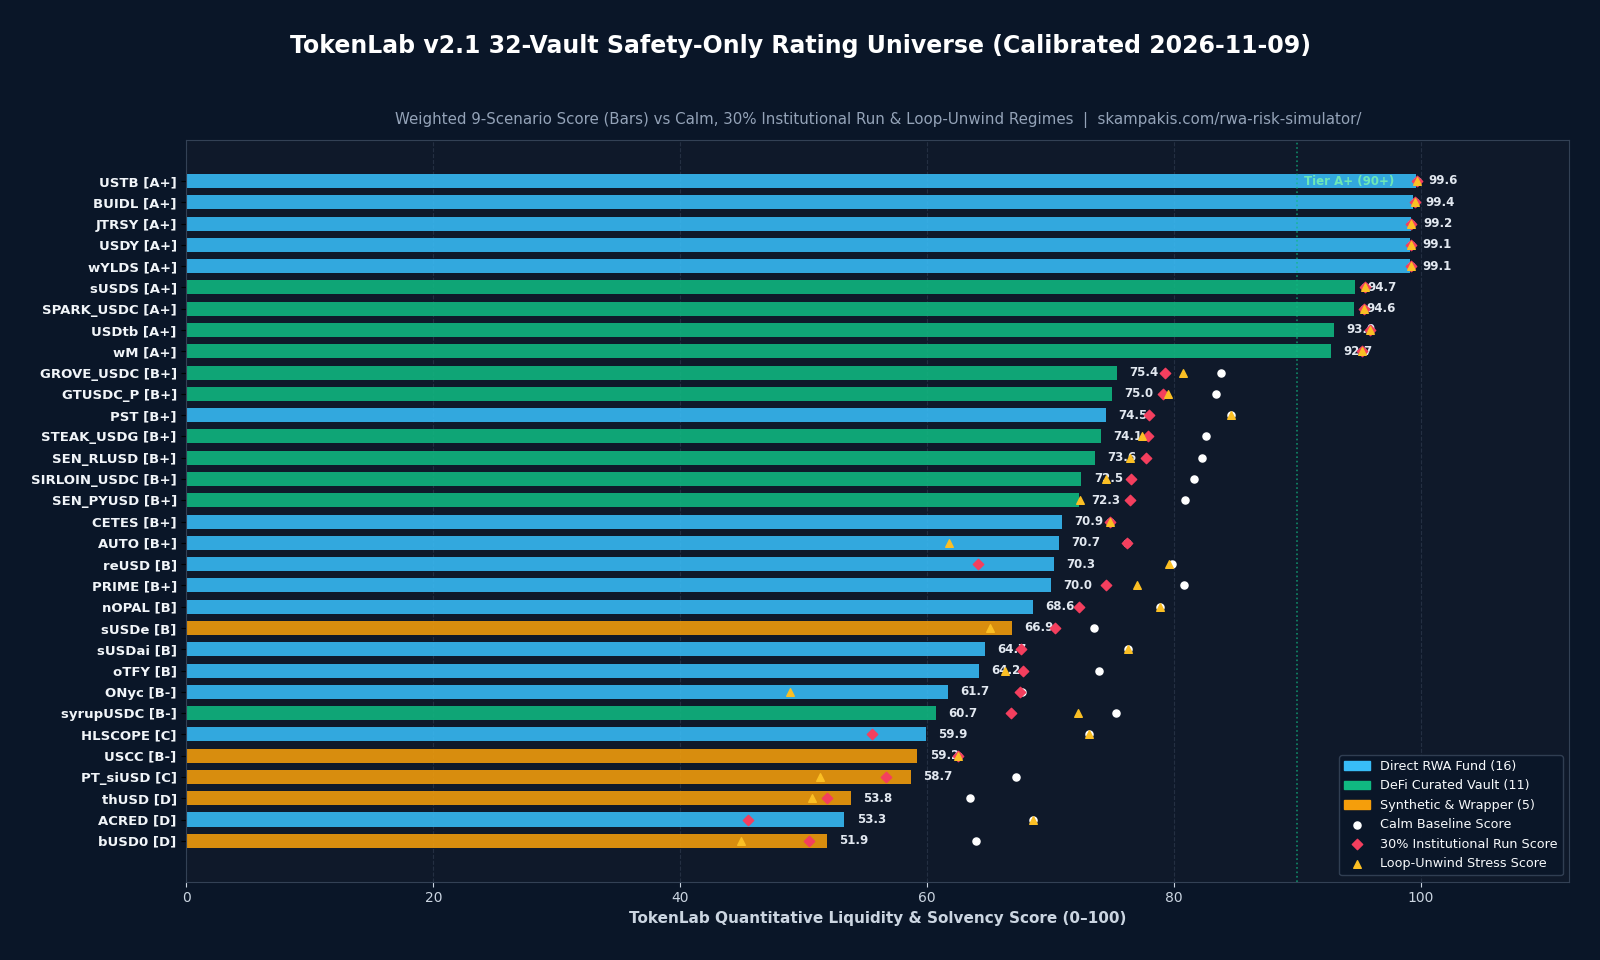
3. Four-Pillar Safety Decomposition, Monte Carlo Distribution & Risk-Compensation Test
TokenLab scores investor protection separately from sponsor fee capture so management or exit fees can never artificially boost a safety grade. Across the 9 stress regimes and 100 Monte Carlo paths per scenario, sUSDe’s 66.9/100 weighted rating decomposes into four pillars:
- Exit Liquidity Pillar (Speed & Secondary Cost): 78.2/100 — penalising any queue formation above immediate T+0 cash clearance.
- Capital Stability Pillar (NAV Drawdown Resistance): 61.1/100 — capturing credit write-downs, basis flips, or mark-to-market duration shocks.
- Liquidity Resilience Pillar (Coverage Ratio Buffer): 61.1/100 — measuring lowest monthly ready-cash plus liquid-facility coverage against maturing claims.
- Risk-Adjusted Yield Pillar (Excess Spread over T-Bills): 63.8/100 — rewarding net spread above sovereign bills without sacrificing principal safety.
Across the Monte Carlo fan distribution, sUSDe’s across-scenario score spans P10 = 61.6 (adverse tail) to P50 = 64.0 (median) and P90 = 66.3 (favourable tail). Under our direct risk-compensation hurdle (charging a 25% forced-exit probability plus 0.30 volatility price of risk above sovereign T-bills), sUSDe delivers an excess spread margin of +0.06%/yr (compensated) with a sponsor break-even AUM threshold of USD 37.2M and reverse-stress SLA breach threshold: No SLA breach observed across reverse-stress withdrawals up to 100%.
Key Risk Driver & Flagged Modelling Assumption: Share of instant liquid USDtb/T-bill reserve (8% baseline) vs delta-neutral perpetual basis positions during negative funding regimes + 7-day cooldown queue. Committees reviewing sUSDe should stress-test both base utilization and correlated oracle/bridge congestion inside the interactive simulator before approving production caps.
4. Safe Lending LTV Governance, Peer Benchmark & DeFi Looping Sensitivity
When RWA tokens or ERC-4626 vaults enter DeFi money markets (Morpho, Aave V3, Pendle, Kamino), governance councils must set Borrowing LTV below 1 - worst_exit_discount - liquidation_buffer rather than copying calm-market volatile-asset parameters. For sUSDe (currently 35% looped on-chain), our v2.1 LTV optimiser recommends a Max Safe Borrowing LTV of 84.0%, a Liquidation LTV of 90.0%, and a per-venue Supply Cap of USD 215M.
| Vault | Architecture | Grade (Score) | Calm APY | 30% Run Wait / Disc | Looped % (Drop) | Safe LTV / Cap |
|---|---|---|---|---|---|---|
| sUSDe (This Vault) | Synthetic & Wrapper | B (66.9) | 4.67% | 1 mo / -0.13% | 35% (drop 8.4) | 84.0% / USD 215M |
| USDtb | DeFi Curated Vault | A+ (93.0) | 3.76% | 0 mo / -0.00% | 0% (drop 0.0) | 87.0% / USD 142M |
| USCC | Synthetic & Wrapper | B- (59.2) | 7.12% | 0 mo / -0.00% | 0% (drop 0.0) | 86.5% / USD 29M |
| PT_siUSD | Synthetic & Wrapper | C (58.7) | 9.31% | 2 mo / -1.54% | 45% (drop 15.9) | 80.0% / USD 8M |
| BUIDL | Direct RWA Fund | A+ (99.4) | 3.76% | 0 mo / -0.00% | 0% (drop 0.0) | 89.5% / USD 250M |
Table 2 highlights the strategic trade-off for allocators targeting keywords like susde: higher yield often disguises either thin cash buffers or multi-week settlement queues during coordinated DeFi deleveraging.
5. Structuring Upgrade Prescription & Live Counterfactual Testing
Crucially, ratings in TokenLab v2.1 are actionable engineering diagnostics rather than static labels. Applying our automated counterfactual stress-fix prescription shows the exact capital cost required to harden sUSDe for institutional balance sheets:
Prescription: Holding a 22% cash reserve with a 1-month settlement cycle and lower DeFi looping eliminates the withdrawal wait (0 months) and raises the Liquidity Stress Score to Band A (77.4/100).
Stress-Test sUSDe Live in Under 30 Seconds
Adjust cash buffer %, asset settlement lag, redemption gates, or Kamino/Morpho looped share in your browser using the exact accrual-basis stock-flow engine behind this report:
Launch sUSDe Simulator → View Full 32-Vault Rating Directory
6. Related Research & Methodological Citations
Explore the full cross-domain research series and underlying empirical references:
- TokenLab 32-Vault Interactive RWA Risk Simulator
- 10-Week Standalone RWA Risk Ratings Observatory
- Why On-Chain Yield Is Not On-Chain Liquidity (Original Study)
- The Data Science Problem Solving Framework: From Business Goal to Solution
- How to Choose an AI Keynote Speaker: A Checklist for Event Organisers
- Enterprise AI in Practice: From Narrow Algorithms to Autonomous Systems
- Ethena Protocol — Official sUSDe Staking, Cooldown & Delta-Neutral Backing Documentation
- Python 3 Scientific Computing & Simulation Runtime Official Documentation
- TokenLab Open-Source Agent-Based & Stock-Flow Simulation Repository (GitHub)
- Diamond, D. W., & Dybvig, P. H. (1983). Bank Runs, Deposit Insurance, and Liquidity (Journal of Political Economy)
- Board of Governors of the Federal Reserve System — Selected Interest Rates (H.15 Sovereign Benchmark)
7. Frequently Asked Questions on sUSDe Risk & Liquidity
1. What is sUSDe’s TokenLab v2.1 Public Safety Rating and why did it receive Grade B?
sUSDe (Ethena) scores 66.9/100 (Grade B) across 9 macroeconomic and liquidity stress scenarios calibrated as of 2026-11-09. Its composite reflects a 4.67% baseline net APY, a 8.0% ready cash buffer, a 1-month maximum queue under a 30% withdrawal run, and 35% on-chain leveraged looping exposure.
2. How much lending leverage and supply cap is safe for sUSDe on Morpho, Kamino, or Aave?
Our stress-calibrated collateral framework sets sUSDe’s Max Safe Borrowing LTV at 84.0% with a hard Liquidation LTV at 90.0% and a recommended protocol supply cap of USD 215M across Morpho, Aave V3, Pendle, Kamino.
3. What happens to sUSDe under a 30% institutional redemption run or DeFi looping unwind?
In Scenario 4 (30% institutional run), sUSDe exhibits a 1-month maximum queue wait and a -0.13% no-arbitrage immediate-exit discount vs NAV. In Scenario 9 (DeFi looping unwind), with 35% of supply looped, its investor score moves from 73.5 to 65.1.
4. How does sUSDe compare against sovereign T-bill benchmarks like BlackRock BUIDL and Superstate USTB?
In TokenLab v2.1, sovereign Treasury-bill benchmarks lead the 32-vault universe: USTB scores 99.6 (A+) and BlackRock BUIDL scores 99.4 (A+) with 0 months queue wait and 0.00% exit discount across all 9 regimes, whereas sUSDe earns 4.67% net APY against a 66.9/100 weighted safety score.
5. Can structuring changes upgrade sUSDe’s TokenLab Safety Rating?
Holding a 22% cash reserve with a 1-month settlement cycle and lower DeFi looping eliminates the withdrawal wait (0 months) and raises the Liquidity Stress Score to Band A (77.4/100). Readers can test any cash reserve, gate, or looping counterfactual live in the TokenLab RWA Risk Simulator.
Disclaimer: This quantitative research briefing is published for informational and risk-engineering discussion only by Dr Stylianos Kampakis and Linas Stankevičius and does not constitute investment, legal, or tax advice. Verify live issuer disclosures and run custom parameters at skampakis.com/rwa-risk-simulator/.
Building Autonomous AI & Data Agents with Python
Learn to architect, evaluate, and deploy autonomous LLM agents with Python and LangChain.